Howden Re’s Mohammad Faizan Huq, associate president and head of treaty reinsurance for agriculture and climate risk, and Mike Xin, managing director and head of agriculture, explore how climate volatility, evolving government programmes and changing risk-sharing structures are shaping underwriting, pricing and demand for reinsurance capacity.
Against the backdrop of El Niño, agricultural insurers in India and China are assessing the impact of the 2026 season and preparing for the 2027 renewals.
In China, central government sets policy for the nationwide scheme and funds close to 80% of premiums through subsidies, with provinces adding specialty products of their own.
Around 30 qualified insurers underwrite and service the business, and reinsurance combines a policy-oriented cession with capacity from more than 60 market reinsurers.
In India, the scheme covers production risk, taking seasonal input cost as sum insured at acreage level.
Central government designs the framework, states decide how to implement it, and premiums are shared between central government, states, and farmers.
Insurers bid for clusters of districts in multi-year tenders, and reinsurance is placed through treaties in the open market, led by GIC Re and other global agriculture reinsurers.
China’s agricultural sector is further professionalising as production shifts towards larger farms and agribusinesses.
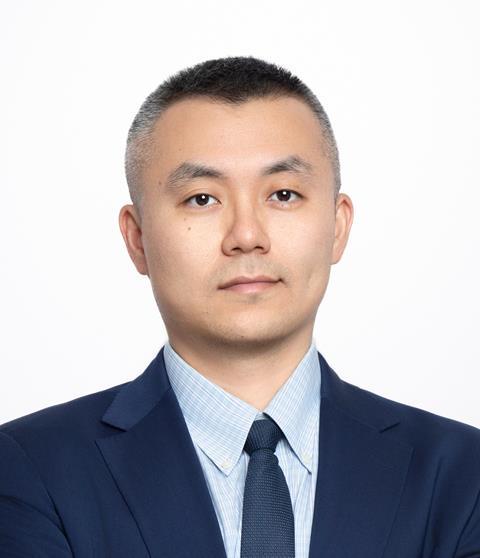
Xin (pictured, top) says: “The agenda has moved from expanding take-up towards deeper protection, better service quality and long-term sustainability, in step with the government’s food-security objectives.”
For major grain crops, that means cover extending beyond input costs to full-cost and revenue protection.
India’s national crop insurance scheme, PMFBY, has kept its core features since 2016, but several states have adopted alternative risk transfer mechanism (ARTM)- 80:110 and 60:130 cup-and-cap models.
Under these arrangements, the insurer and government share premium surplus and losses according to specified loss-ratio thresholds and the applicable tender terms.
These structures change the risk retained by insurers and, consequently, the reinsurance protection required.
These ARTMs have contributed to lower premium rates in some portfolios, although changes in coverage, competition, exposure and tender terms also influence pricing.
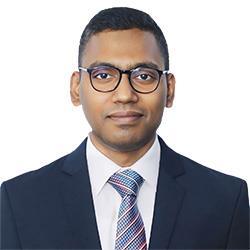
Huq (pictured, next) says: “With implied rates falling by around 30% on the previous year whilst sums insured rose by around 28% during the 2026 Kharif (monsoon) season, for capacity providers, rate adequacy is now the central question.”
How is climate changing the way risk is priced?
In both markets, the 2026 season has highlighted the potential for widespread and correlated agricultural losses.
El Niño is one factor influencing weather patterns, but local outcomes also depend on other climate drivers, rainfall distribution, crop stage and regional conditions.
For insurers and reinsurers, the key challenge is to understand how these factors can accumulate across crops and regions.
India’s SW Monsoon rainfall ended the season with more than 12% deficit. In Karnataka, which experienced a 35% rainfall deficit, crops on around 5.5 million hectares were reported damaged.
In Maharashtra, around 9 million hectares were affected, (according to media reports) with some districts reporting losses of up to 80% of expected yields.
“Multi-year tenders lock in premiums for three years, so with these conditions, pricing needs enough buffer to absorb climate-driven losses across the cycle,” says Huq.
“That means appropriate catastrophe loading for drought- and flood-prone districts,” he adds.
China’s Official data indicates that natural disasters affected 1.70 million hectares of cropland in the first half of 2026. In the affected areas floods and geological disasters accounted for 852,100 hectares.
Overall, these events resulted in direct economic losses totalling RMB 42.1 billion.
“To be effective, risk analysis must move beyond single-peril averages to consider location, sequences of events and regional accumulation,” says Xin.
“Cedents should treat historical experience and climate projections as separate inputs, using projections to stress-test portfolios,” he adds.
How is the public–private partnership evolving?
In both countries, government policy sets the direction, and public and private (re)insurers deliver it through market-based mechanisms – a partnership that continues to evolve.
In China, government sets policy, subsidises premiums, regulates and provides policy-oriented reinsurance, while insurers deliver the scheme.
The September 2026 national plan calls for more precise underwriting, better claims standards and shared data. It also points to combining policy-oriented and market reinsurance, stronger catastrophe excess-of-loss protection and a possible agricultural catastrophe risk fund.
“These developments create a clear role for reinsurers in severe years and in more volatile classes,” Xin says. “Cedents would do well to map how government-initiated cover interacts with commercial reinsurance layers.”
The protection gap is now about adequacy rather than take-up. “Grain schemes are extensive, but limits may not match producers’ actual cost or revenue exposure,” says Xin.
“Cover for specialty crops, livestock and aquaculture also varies by region, and the 2026 plan encourages market-based cover for supply-chain risks,” he says.
In India, the central government designs the scheme, sets operational guidelines in discussion with all the stakeholders and define fiscal subsidy share structure between centre and state government.
The cup-and-cap models described above mean government now shares in both surpluses and losses above a cap, and the proposed changes to the 2027–2030 tender cycle is expected to widen coverage and raise indemnity levels.
“Reinsurers with US and Chinese experience can add real value through good practice, pricing efficiency and technology,” says Huq. “They should also look beyond quota share and stop loss to structures that fit the new risk-sharing models.”
Where China’s gap is about adequacy, India’s is about reach.
“There is scope to take insured-area penetration from around 30% towards 50%, with indemnity and index-based solutions suited to each crop and region,” says Huq.
Xin says: “In both markets, cedents and reinsurers should bring proven designs from other markets, invest in the data that make new cover insurable, and agree clear roles with the public sector.”
What role for data, technology and parametric?
This is where the two markets are most closely aligned. In both, satellite imagery, remote sensing, drones and tech-based yield estimation increasingly underpin underwriting and claims.
But remote indicators alone do not establish yield loss,” says Mike Xin. “Data standards, ground validation and clear claims rules remain essential.”
India’s scheme already uses weather-index cover for horticulture. “Given how erratic the monsoon has become, there is a strong case for more,” says Huq.
“A rainfall-based catastrophe cover could protect portfolios against severe drought like this year’s in Maharashtra and Karnataka,” he adds.
In China, parametric cover is gaining ground in the classes where traditional protection varies most by region, such as aquaculture and specialty crops.
Defined typhoon or heat triggers for aquaculture, for example, can pay out quickly and transparently after an event, without waiting for a full field-by-field loss assessment.
“These more volatile classes, and the parametric products designed for them, are where reinsurers can add real value,” says Xin.
“In both markets, cedents should use parametric cover as a top layer that complements indemnity. Triggers should be back tested against observed losses, and basis risk monitored closely,” he says.
Outlook
With tenders and treaty renewals due in the first half of 2027, attention is turning from what this season has cost to how next year’s programmes will be priced, structured and supported.
China enters 2027 with a market still growing at around 4–5% a year and a new national plan reshaping underwriting, claims and catastrophe risk sharing.
The coming renewals will be the first to reflect both this year’s weather losses and that policy shift.
“Cedents should turn 2026’s typhoon, flood and drought experience into claims data by region, crop and product, and open renewal conversations early with consistent exposure data,” says Xin.
“Capital providers should weigh price alongside terms, attachment points and data quality, using climate outlooks to inform scenarios rather than replace observed losses. Implementation of the 2026 plan and the catastrophe risk fund proposal are the ones to watch,” he adds.
For India, the 2026–2027 season is expected to bring above-normal losses, and the wider coverage expected from the 2027–2030 tender cycle changes are likely to increase exposure.
Together, that will put pressure on capacity at 2026 rates.
Huq says: “Pricing discipline in tender bidding would do much to build reinsurers’ confidence, and structured solutions can take insurers beyond conventional quota share and stop loss.”
In both markets the 2026 season has shown how quickly a single climate driver can test portfolios across a whole country.
As the 2027 renewals approach and policies evolve, the cedents that combine disciplined pricing with transparent data and a willingness to explore new structures will be best placed to secure capacity on sustainable terms.
“In both markets, the answer to address these challenges, will depend as much on the quality of information cedents bring to the table as on the capacity available,” Huq adds.
No comments yet