Low insurance penetration, stronger underwriting results and plentiful reinsurance capital are creating new opportunities across Asia-Pacific as insurers pursue international expansion, specialty business and emerging technology risks
Artificial intelligence (AI), international expansion and abundant reinsurance capital are reshaping insurers’ growth strategies across Asia-Pacific, according to Gallagher Re.
Its latest “APAC Market Watch” report found the 14 markets analysed grew by an average 4.4% in 2025, compared with global GDP growth of 2.9%.
Emerging Asian economies expanded by 5.3%, compared with 2.1% across the seven mature markets covered by the reinsurance broker’s report.
However, regional non-life premium growth slowed to 5.1% from 7% in 2024, its lowest rate since 2021, reflecting softer pricing in several mature markets and portfolio pruning elsewhere.
Gallagher Re said the underlying opportunity remained significant, with non-life insurance penetration averaging just 1.1% across Emerging Asia, compared with 2.3% in Mature Asia.
India, Vietnam and the Philippines all have penetration below 1%, despite relatively strong economic and premium growth.
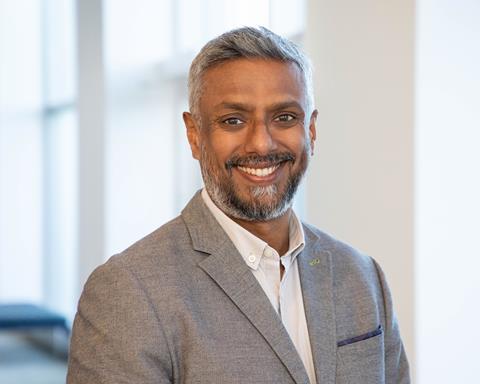
Roshan Perera (pictured), CEO, Asia Pacific at Gallagher Re, said: “Asia Pacific remains one of the most compelling long-term growth markets for the global insurance industry.
“Strong economic growth, low insurance penetration across many markets and increasing investment in infrastructure, technology and energy transition initiatives are creating substantial opportunities for insurers throughout the region.”
Profits drive search for growth
The report found the slowdown in organic premium growth has coincided with improved profitability and capital accumulation, increasing pressure on management teams to find alternative ways to deploy capital.
Average combined ratios across the region improved from 99.4% in 2024 to 98.1% in 2025.
Emerging Asia moved from an average underwriting loss at 101% to 99%, while Mature Asia improved from 97.5% to 97%.
Against this backdrop, insurers are increasingly looking overseas.
“Internationalization through M&A to date has focused on specialty lines and reinsurance, market segments that have shown strongly improved profitability and growth over the past three years,” the report said.
Japanese insurers have been particularly active, including Sompo’s acquisition of Aspen and MS&AD’s investment in W.R. Berkley, while Korean insurers have also sought international growth.
For carriers without established overseas platforms, Gallagher Re said third-party reinsurance, MGAs and Lloyd’s offer relatively low barriers to entry.
AI becomes an insurance exposure
AI is also moving beyond its role as an operational tool and increasingly becoming an insurable risk.
“Across Asia Pacific, artificial intelligence is no longer confined to pilots and innovation teams,” the report said.
“The issue for insurers is that the risk is moving faster than many policy wordings, rating models and accumulation controls were built for.”
Gallagher Re said AI-driven investment in semiconductors, data centres, energy storage and digital infrastructure is increasing insured values and generating opportunities across property, engineering, cyber and specialty insurance.
At the same time, AI errors, intellectual property infringement, privacy breaches and automated decision-making can cut across cyber, professional indemnity, product liability and other classes.
One in five insurance professionals surveyed separately by Gallagher said a client had experienced an AI-related loss or claim during the previous year, while only just over half said the loss had been fully covered.
Reinsurance market favours buyers
Reinsurance conditions are providing insurers with additional flexibility heading into 2027.
Gallagher Re said the Asia-Pacific market “remains firmly in buyers’ favor”, supported by ample capacity, strong reinsurer balance sheets and continuing competition.
“The more important consideration for insurers today is not that reinsurance is becoming cheaper, it is how best to utilize the current market environment to achieve their strategic objectives,” the report said.
Cedants have an opportunity to reconsider retentions, earnings volatility and capital efficiency while using cheaper capacity to support expansion into new products and markets.
Gallagher Re expects supply to remain ahead of demand through the upcoming renewal season, although a major catastrophe, renewed inflation or capital market disruption could slow or reverse softening.
Perera said: “At the same time, strong balance sheets and abundant reinsurance capacity are giving insurers more strategic flexibility than they have had in recent years.
“Organizations that can combine underwriting discipline with innovation will be best positioned to capitalize on the next phase of growth across Asia Pacific,” he added.
No comments yet