Earnix’s Agent Hub aims to accelerate insurers’ pricing and underwriting work while preserving human oversight, with Matthew Twist arguing that governance and integration will determine the technology’s value
Insurers need a controlled environment for deploying artificial intelligence (AI) agents across their businesses, according to Matthew Twist, vice president, sales, EMEA, at Earnix.
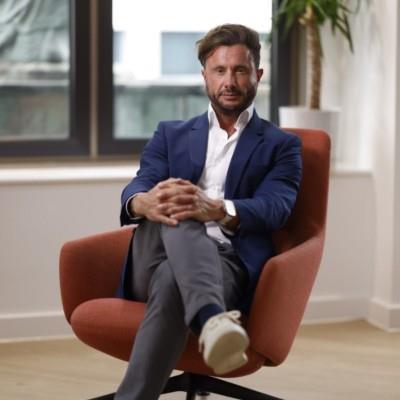
Speaking at the company’s London conference in September, just weeks after joining the insurtech provider in August, Twist said its newly announced Agent Hub would allow insurers to combine Earnix’s agents with their own and third-party tools, linking tasks across existing systems.
“I think the real crux for me is it’s that controlled environment, and that’s a differentiator,” said Twist (pictured).
Part of Earnix’s AI Orchestration System, Agent Hub was announced with a catalogue of more than 25 insurance-specific agents and apps spanning pricing, underwriting, modelling and customer engagement.
Human oversight remains central
Twist described the agents’ role as undertaking analytical work while leaving people responsible for strategic decisions.
Tasks include analysing model drift, extracting submission data and explaining underwriting recommendations.
“It’s allowing the actuaries to perform heavyweight tasks from the agent that they’d have to go and crunch these numbers themselves,” he said.
For Twist, pricing and rating provide a natural starting point for that strategy because of their central role in insurers’ financial performance.
“Pricing and rating is the brain of the insurer,” he said. “It’s effectively their mechanism for how they make money.”
The proposition also depends on insurers being able to understand and investigate agents’ activity, removing so-called black box issues arising from a lack of transparency.
“They’re fully auditable, controlled, and any prompt is recorded, and you can go to root cause analysis of what’s happening with the agent,” Twist said.
Connecting existing systems
Earnix’s approach is designed to work across insurers’ existing infrastructure, including policy administration systems, without requiring their replacement, he explained.
“The overarching vision is that we’re the orchestration layer above existing infrastructure,” Twist said.
He outlined how agents could extract information from a submission, assess it against an insurer’s risk appetite and pass that information into pricing and rating processes.
Other agents could analyse model impacts, drawing on different data sources.
The intention is to connect those activities across a workflow, with insurers able to contribute their own technology.
“You can import your own agents or you can build your own agents in there,” he continued.
Speed and competitive advantage
Twist argued that faster responses to changing market conditions could help insurers to better protect margins in a competitive market.
Established processes can leave companies taking months to react, making the speed of analysis and implementation commercially significant.
“That’s the weapon: speed. How quickly can you react to the softening market?” he said.
Using common technology would not remove competitive differentiation, he added. Insurers would retain their own data and strategic choices about pricing risk.
“It’s just you’ve got someone doing the legwork quicker, or an agent doing it quicker than you or I could, or a bunch of us could do,” Twist added.
No comments yet