European wildfires have barely affected property catastrophe treaties, but changing exposures and gaps in modelling demand closer attention, says the reinsurance broker’s head of international catastrophe and actuarial analytics, Tim Edwards
Europe’s wildfire losses remain small relative to the attention they attract, but insurers need a better understanding of where future claims could accumulate, according to Howden Re’s Tim Edwards.
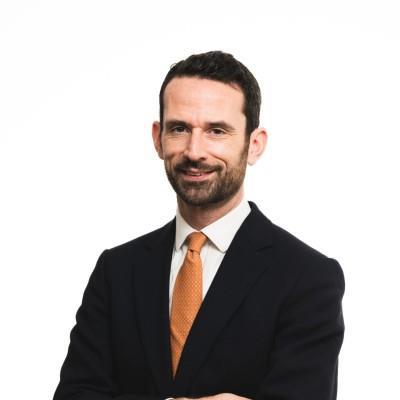
“Wildfire has over the last 10 years accounted for less than 1% of European insured losses,” he said.
Recent events have had little impact on property catastrophe treaties, with losses well below those experienced in North America and Australia.
Edwards cautioned against equating dramatic images and extensive burnt areas with substantial insured damage.
“It’s a very visual peril, and it does cause damage to infrastructure and supply chains,” he added.
Losses emerge through other covers
European buildings’ lower flammability compared with North American and Australian construction, alongside fewer properties close to forests, has helped contain losses, Edwards said.
Limited insurance penetration also leaves some exposures uninsured.
However, claims are reaching other parts of the market, he suggested.
“Where it is an issue is on fire treaties,” Edwards said. “Some fire treaties allow the aggregation of claims within a fire event.”
He cited one southern French fire caused by an abandoned car, where claims were subsequently recorded under motor third-party liability after losses were subrogated against the motor insurer.
“These losses are appearing in sort of ways you wouldn’t necessarily expect,” he said.
Mapping the modelling gaps
Edwards said the major catastrophe model vendors do not adequately model European wildfire, and he wants development to move faster.
“We would like the vendors to be quicker to have coverage for these kind of perils,” he said.
Howden Re’s work has identified Bordeaux and Madrid as two urban areas where population concentrations sit close to susceptible forestry.
Mapping these accumulations provides a starting point for insurers assessing exposure.
The broker is also looking to work with vendors using European fire propagation modelling, climate indicators and building damage studies.
“Although the risk is expanding, it’s very concentrated and localised,” Edwards said.
Preparing for larger losses
Urban development, changing land management and climate conditions could increase the peril’s significance.
“We’ve got urban infrastructure and the continued build out of that, the management of land and agroforestry changing over time, and we’ve got the climate,” Edwards said.
That raises questions about how private insurance markets will respond as concentrations become more material.
Edwards suggested additional capacity and innovation could help strengthen community resilience, while research could support measures to reduce damage.
“We only have to look to the other regions to see how material a loss driver and economic impact it can be,” he added.
No comments yet